 Skip to main content

Tatarstan Halal Foods: The Confectionery Mirage
In December 2023, a company called Fabrika Bahetle-1 registered in Zelenodolsk, Tatarstan, where more than ₽600 million went into a factory's first phase. Its owner of record was Muslima Latypova's grandson. Latypova, decades into running the business she founded, was not stepping down — she was building the one asset her retreating retail chain could no longer carry alone.
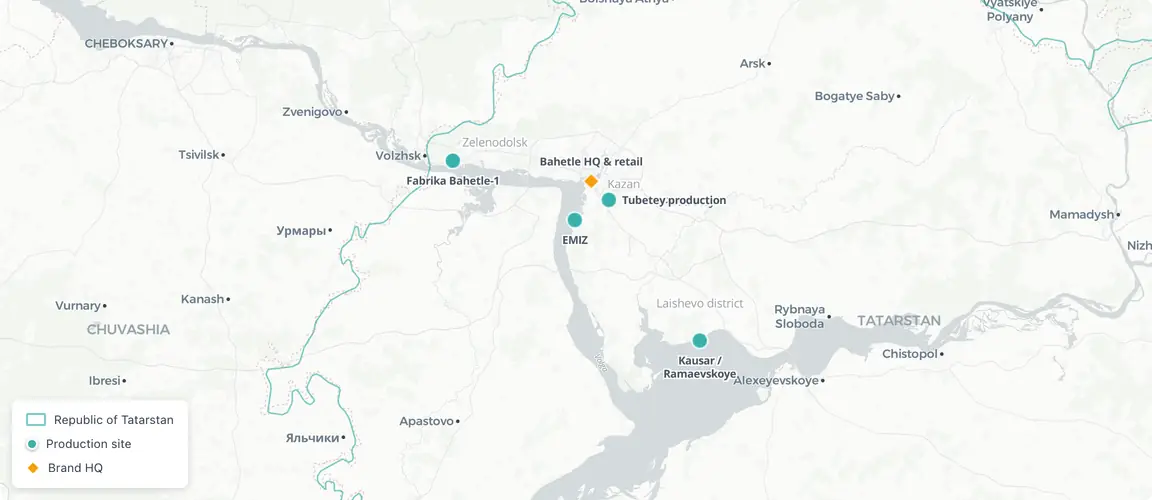
Tatarstan's Food-Production Cluster
Four brands, one production geography around Kazan
Retreat as strategy, twice
Two of Tatarstan’s best-known food brands have spent the last several years shrinking their public-facing footprint — one closing stores, the other closing franchise locations — and neither founder describes it as decline. Neither describes it as a defeat. What each kept, while the storefronts and outlets fell away, was the part of the business a competitor or a franchisee defection can’t simply take: the production line, run under direct family or founder control.
The shop that shrank, the factory that grew
We are leaving those stores where we have no customers.
Bahetle (Бахетле) is Tatarstan’s best-known specialty food retailer — the premium supermarket chain Latypova opened on Kazan’s Sibirsky Trakt (Сибирский тракт) in December 1998, built from the start on roughly 40% own-production Tatar prepared food (closer to 50–60% in its Moscow stores). It grew for nearly two decades, peaking at ~₽10.14 billion in revenue in 2016 — the year the brand was, by most measures, the definitive regional retail story to come out of Tatarstan, a regional operator that had out-lasted and out-scaled the corporate chains crowding into the same shelf space. Its halal store, Bahetle-Halal in Kazan’s Old Tatar Quarter, opened under DUM RT certification in January 2014 and closed in 2023.
Then it began contracting. By 2024, revenue had roughly halved to ₽4.63 billion and net profit had fallen to just ₽8 million; in April 2026 the chain’s once-multi-store Moscow presence ended when its last store, on Tverskaya (Тверская) street, closed. For a brand whose entire premise had been that Tatar prepared food, done at premium quality, could compete for shelf space against federal grocery chains in Russia’s most contested retail market, that contraction reads — at a glance — like a story about a heritage retailer losing to scale.
Latypova has been explicit that this is not surrender. “We are leaving those stores where we have no customers,” she told Business Online in 2023, rejecting comparisons to other regional retailers who ceded shelf space to federal chains outright. On another occasion she put the ownership question even more plainly: “I didn’t just stand at Bahetle’s origins — I am the company’s founder. This is my intellectual property, and no one can remove me from management.”
What she has not stopped building is the production side. In 2020, her daughter Elvira Kharlamova founded a dedicated manufacturing entity, Fabrika Bahetle (Фабрика Бахетле) — the first formal step in separating the brand’s durable asset from its exposed retail estate. Three years later, her grandson Erik Kharlamov registered a second entity, Fabrika Bahetle-1, in Zelenodolsk, where more than ₽600 million had gone into the first phase of a 30-tonne-per-day semi-finished-food factory. The retail chain that made Bahetle a household name in Kazan is contracting. The production infrastructure that actually makes the food is scaling, under family control, across two generations.
The sequencing is the tell. Latypova did not wait for the retail estate to fail before building the succession — she started while the business was still generating real (if declining) revenue, and she structured it as two separate, dated, publicly registered entities rather than an informal handover inside the existing corporate shell. Zelenodolsk itself is not an accidental choice: the town sits inside a designated tax-incentive zone (a TOSER, Territory of Advanced Socio-Economic Development), the kind of location a founder picks when she is optimizing a production asset for decades, not managing a retail portfolio for the next quarter. Three generations removed from the original 1998 storefront, what Latypova actually owns and controls today is not a chain of supermarkets. It is a production and intellectual-property base she has been quietly relocating to family hands since 2020 — visible in public filings to anyone who checked, and apparently invisible to any institutional database that tracks “Russian retail chains in decline” without asking what a declining retailer is doing with its balance sheet.
A different brand, the same instinct
Tubetey (Тюбетей) tells a version of the same story from a different starting point. Sultan Safin and his co-founders opened their first pavilion in Kazan in June 2015 and six more for the world aquatics championships that summer. Growth came through pavilions and franchises: by November 2018 Tubetey ran 17 points of its own formats, franchises included, and 82 shops in 20 cities stocked its frozen goods. Then quality failed at franchisees. In February 2019 the Naberezhnye Chelny franchise was withdrawn, and by June 2019 Tubetey was down to two restaurants and two pavilions of its own.
Safin’s response was not to rebuild the franchise count. Tubetey kept its own central kitchen, where its pastries have been made by hand since 2015, and rebuilt in Kazan restaurant by restaurant, with investor partners. By early 2026 it counted about ten investor partners and between about 11 and 17 restaurants, including Zaman in Ufa — a model built for control, not just count.
The idea itself long predates the contraction. Safin, then a geology student in Kazan, has said it came to him on an internship in China in 2010; he and Ainur Kamaliev chose the name in 2011. A founder who started from a cultural idea rather than a franchise model responded to his network’s contraction by rebuilding smaller and tighter around the actual product — not by chasing the franchise count that had briefly made the brand look bigger than its production base could support.
Two founders, two very different businesses — a supermarket chain and a fast-food operator — arrived at the same structural answer. When the customer-facing footprint became the liability, both retreated from it and consolidated around the thing a franchisee defection or a federal competitor cannot easily take: production under their own direct control — for Tubetey, under DUM RT halal certification. Neither treated the retreat as a story to hide. Latypova gives interviews about it. Safin, looking back in 2025, called the franchising an “adventure” the company closed within a year — the account of a founder for whom the shrinkage was a decision, not something that happened to him.
The export number that isn’t about them
Tatarstan’s halal sector has a headline figure institutional readers are more likely to have seen than either of these companies: exports grew roughly eighteenfold since 2020, from $2.5 million to $45 million in 2025. Rustem Gaynullov, the region’s Deputy Minister of Agriculture and Food, confirmed the trajectory directly in January 2026 — “roughly $45 million in our halal-product exports” — and added the qualifier that matters most: “mostly confectionery, around 80%.”
That 80% belongs to a different sub-sector entirely — confectionery exporters like Essen and Akulchev, whose full story sits in Brandmine’s separate Packaged-Food FMCG coverage of this region. It does not belong to Bahetle, Tubetey, EMIZ, or Kausar — the retail, fast-food, beverage, and meat producers this article covers. The export headline is real. It is also, for a reader trying to find the founders behind Tatarstan’s food sector, actively misleading — the number that gets cited is the number that hides them.
None of this happened by accident of certification infrastructure.
DUM RT’s Halal Standard Committee — the Spiritual Administration of Muslims of Tatarstan’s dedicated certifying body, formally constituted in 2008 — spent over a decade building the credibility that let a Gulf Cooperation Council accreditation team audit it directly in September 2024, and let it become, in 2025, the first Russian certification body with full state accreditation under GOST R 70402-2024. Abbyas Shlyaposhnikov (Аббяс Шляпошников), who heads that committee, has stated the export trajectory in his own words: “Back in 2020, halal-product export from Tatarstan totaled just $2.5 million. By 2023 it had grown to $11 million. By the end of 2024 it reached $14 million, and in 2025, $45 million.”
That infrastructure is what any halal producer here now exports against. It is also what made the trust collapse of June 2018 — when a World Cup-branded halal sticker turned up on pork at Chelny-Myaso (Челны-Мясо), and DUM RT suspended the company’s certification rights — a moral rupture, not a routine regulatory infraction. Tatar halal identity is not an imported Gulf construct; it traces to Volga Bulgaria’s thousand-year Islamic history and to dishes that predate any certification body. That is exactly why the sector’s most culturally distinctive product exports worst: kazylyk, cured horse meat, is deeply Tatar and has little Gulf or Arab demand. Export success in this sector flows disproportionately to religiously neutral categories — confectionery, and, within halal food itself, beverages like EMIZ’s — while the meat producers who carry some of the sector’s strongest founder stories export against a harder market.
The 2018 shock is also why a brand like Kazanskie Delikatesy (Казанские Деликатесы) — a private-label sausage and delicatessen producer registered in a Kazan agropark in late 2022, certified by DUM RT in February 2023, now supplying, by its own account, both Bahetle’s stores and the EuroSpar retail chain — matters to this sector even though its founder story remains thin. Its sole confirmed owner appears only in Russia’s corporate register, with no independent press profile to draw a fuller picture from; even so, the company itself is a legible data point about the sector’s post-scandal shape: certification rigor is now a market-entry credential a new producer builds a business plan around from day one, not a compliance afterthought bolted on after the fact.
What a buyer would actually be buying
EMIZ, founded by Rail Fazulzyanov in 2019, has quietly built the sector’s most internationally diversified halal-certified export book — a grape-seed beverage producer, not a meat brand: roughly 30% of its shipments now go to Gulf countries, alongside growing volumes to Uzbekistan and a planned vineyard investment there in 2026. Kausar, the vertically integrated duck operation Farid Khairutdinov has run near Kazan since 2011, exports to Kazakhstan and Uzbekistan; well into his career, no public record yet shows a named successor, which is the same transition question Bahetle’s has already begun answering.
Both point to the same underlying asset class this sector actually trades in: not retail square footage, not franchise counts, but production capacity under a founder or successor who controls it directly — with, for an exporter, a defensible halal chain of custody on top. Bahetle’s is the clearest version of a production asset changing hands on purpose. Fazulzyanov’s is still concentrated in one pair of hands with real Gulf-market traction. Khairutdinov’s is the version still waiting for a decision.
The three-way distinction matters because it tells an investor or importer where they are actually looking at an opportunity and where they are looking at a countdown. Bahetle’s succession is mid-transition, not finished — the family structure that will eventually own the production assets outright is still being built, generation by generation. Separately, DUM RT’s Gulf accreditation is still new enough that most Gulf importers haven’t priced it in yet for the producers it certifies. That is the window this article is naming: not “Tatarstan halal food is growing,” which the export headline already tells anyone who looks, but which specific, currently-transitioning production assets are worth engaging before the transition completes and the terms of engagement change.
The window that isn’t the same for everyone
Khairutdinov’s Kausar is the version of this story with no clock yet visible from the outside. Running a vertically integrated duck operation — his own parent stock, incubators, farms, slaughter, and processing — that already exports to Kazakhstan and Uzbekistan, he is well past the career stage at which Latypova had already begun her own succession moves. No comparable Fabrika Bahetle-1 has surfaced in Kausar’s public record. That is simply what the public record does and doesn’t show — a succession plan may exist without ever having been filed or reported — but it is the sharpest contrast this sector offers to Bahetle’s documented transition. A buyer or partner approaching Kausar today is approaching a business whose durable asset — the certified, vertically integrated production chain — carries no publicly confirmed line of succession yet.
Fazulzyanov’s EMIZ sits at the opposite end of that same spectrum. A generation younger than Khairutdinov, with Gulf shipments already running near a third of total volume and a planned Uzbekistan vineyard investment for 2026, EMIZ looks less like a succession story and more like a founder actively building the asset an eventual buyer would want to inherit — years, not decades, into that process. Read the three side by side — Bahetle’s succession already documented and in motion, Fazulzyanov’s asset still being actively built by a founder mid-career, Khairutdinov’s asset carrying no visible plan on the public record — and the sector stops looking like one halal-export growth story and starts looking like three separate clocks, running at three different speeds, none of them reset by the confectionery export figure that gets quoted about all of them at once.
Researched 32 sources in English, Russian.